How Much is Auto Insurance in Massachusetts: A Comprehensive Guide to Understanding Costs and Coverage

So, you’re wondering just how much auto insurance in Massachusetts can set you back, huh? Well, you’re in the right place! Navigating the world of car insurance can often feel like you’re driving through a maze with no end in sight. Luckily, we’re here to break down the essentials for you, straight from the heart of the Bay State.
Massachusetts, with its unique blend of bustling urban areas and serene countryside, presents a distinctive landscape for auto insurance. From mandatory coverages to the factors that jack up your premiums, understanding what influences your insurance costs is key to making smarter decisions. So buckle up, and let’s dive into the intricacies of auto insurance in Massachusetts.
Understanding Auto Insurance in Massachusetts
Did you know that Massachusetts has some of the highest auto insurance rates in the U.S.? If you’re driving in this state, understanding your insurance can save you a bundle.
Massachusetts law requires drivers to carry specific types of auto insurance. These include Bodily Injury Liability, Personal Injury Protection (PIP), and Property Damage Liability. But don’t let the jargon scare you; getting the right coverage is simpler than it seems.
Basic Insurance Requirements in Massachusetts
Every driver must carry a minimum of $20,000 per person and $40,000 per accident in Bodily Injury Liability. Plus, there’s a $5,000 requirement for Property Damage Liability. These are non-negotiable, and you can face hefty fines if caught without them. The catch? These are just the starting points, and many drivers opt for higher coverage to stay better protected.
Factors Influencing Auto Insurance Costs
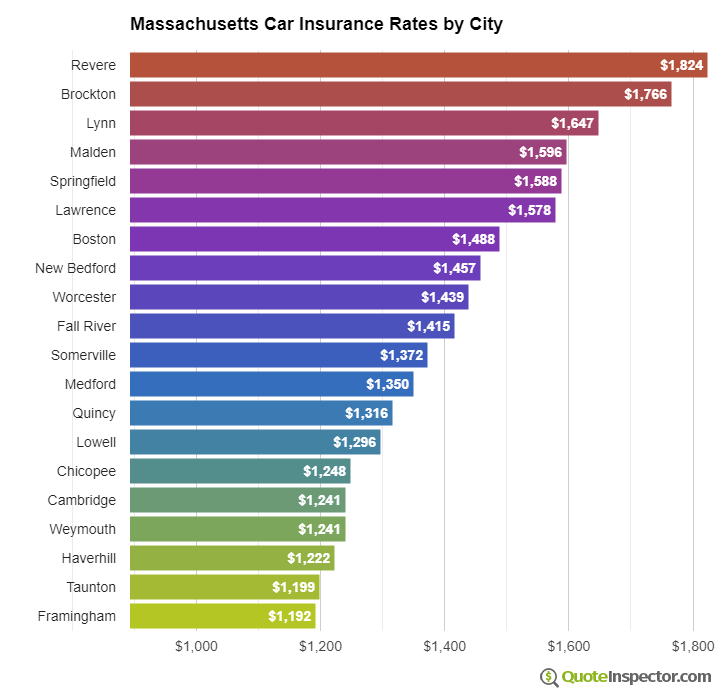
Several factors can affect your insurance premiums in Massachusetts. Your driving record is a big one. A clean record can save you lots of money! Where you live also plays a role. For instance, urban areas like Boston typically have higher rates due to increased accident risk.
Another factor is your vehicle type. Sports cars might be fun, but they can skyrocket your insurance costs. Pro Tip: Consider a more moderate vehicle to keep your premiums manageable.
Mandatory Coverages Required by Law
Let’s break it down. Apart from the mandatory liability coverage, you also need Uninsured Motorist Coverage in Massachusetts. This protects you if you’re hit by a driver with no insurance. The minimum is $20,000 per person and $40,000 per accident, similar to Bodily Injury Liability.
Insurance Policy Variations Across Massachusetts
Here’s the deal: Insurance costs aren’t uniform across the state. If you’re in Boston, expect to pay more than someone in Springfield due to traffic density and accident statistics. Insurance companies look at these factors when setting your rates.
Differences also arise based on local laws and enforcement. Step #1: Always check local regulations. They can provide insights into what affects your premiums specifically where you live.
Cost Factors for Auto Insurance
Are you shelling out more for auto insurance in Massachusetts than your friends in other states? You’re not alone. The Bay State comes with its own set of rules and quirks when it comes to insurance rates.
Understanding these factors can help you save big. So, let’s dive into the unique cost elements that affect your auto insurance premiums in Massachusetts.
Factors Affecting Insurance Premiums in Massachusetts
First off, your *location* plays a massive role. Urban areas like Boston tend to have higher rates due to traffic density and accident risks. Insurance companies will also scrutinize your driving history. If you’ve had a few bumps and scrapes, expect your premiums to skyrocket.
But, that’s not all. The type of car you drive matters too. Insurance companies look at the *make and model* of your vehicle. Luxury cars or models with high theft rates come with heftier price tags. In contrast, a practical minivan can save you some bucks.
Average Insurance Costs in Massachusetts vs. Other States
Here’s the deal: Massachusetts isn’t the cheapest place for auto insurance. According to recent statistics, the average annual premium here is around $1,500. Let’s see how this stacks up against other states:
| State | Average Annual Premium |
|---|---|
| Massachusetts | $1,500 |
| New Hampshire | $1,200 |
| California | $1,800 |
| Florida | $2,000 |
As you can see, Massachusetts is somewhere in the middle. But knowing where you stand can help you negotiate better rates or switch providers.
The Impact of Driving History on Insurance Rates
Let’s not sugarcoat it: a clean driving history is your best friend. Have you ever had an accident or received a ticket? Your premiums will likely soar. Insurers are like elephants; they never forget your past mishaps. They use this data to assess your risk level.
Pro Tip: Keep your driving record clean for at least three years to see a noticeable drop in your insurance rates.
Even a speeding ticket can sting. But the good news? Some companies offer *good driver discounts* if you play it safe on the roads for a set period.
Car Make and Model Influence on Pricing
Ever wondered why that shiny sports car comes with a hefty insurance bill? It’s not just speed that insurers worry about. High-end models often mean high repair costs or a bigger target for thieves. On the other hand, a sensible sedan could keep your premiums manageable.
But it’s not all bad news for car enthusiasts. Some insurers offer discounts for vehicles with advanced safety features. So, if your ride has modern tech like lane-keeping assistance or automatic braking, you might just pay less.
Insurance Providers and Options

Ever wonder how many auto insurance providers are vying for your business in Massachusetts? Well, there are more than you’d think! Let’s dive into the wide range of options you have.
Choosing the right auto insurance provider can feel overwhelming. From national giants to local heroes, the landscape is filled with choices. Picking the right one can save you hundreds of dollars a year. But it’s not just about price; it’s about finding the coverage that fits like a glove.
Popular Auto Insurance Providers in Massachusetts
Here’s a rundown of some of the most well-known insurers offering policies in Massachusetts:
- GEICO
- Progressive
- State Farm
- Liberty Mutual
- MAPFRE Insurance
Each of these companies has its unique perks and downsides. For instance, GEICO is renowned for its competitive pricing, while Liberty Mutual offers a variety of customizable coverage options tailored to your needs.
Coverage Options and Pricing Comparison
The right coverage varies from person to person, so knowing what each insurer offers is crucial. Let’s break it down:
| Insurance Provider | Basic Coverage | Premium Coverage | Average Cost |
|---|---|---|---|
| GEICO | Liability, Property Damage | Full Coverage, Roadside Assistance | $1,100/year |
| Progressive | Liability, Uninsured Motorist | Gap Insurance, Pet Injury Coverage | $1,250/year |
| State Farm | Bodily Injury, Personal Injury Protection | Rental Reimbursement, Rideshare Coverage | $1,300/year |
These prices are averages and can vary based on factors like your driving record, age, and vehicle type. Here is the deal: always get a quote tailored to your specific situation!
Local vs. National Insurance Providers
Deciding between a local and national provider? Each has its pros and cons.
National providers like GEICO and State Farm offer broad networks and stable financial backing. However, local companies often provide personalized customer service and a deep understanding of state regulations.
Pro Tip: If you value personalized service and support, a local provider might be your best bet. But if you’re looking for an extensive range of services and discounts, national companies could be more appealing.
Discounts and Incentives
Who doesn’t love a discount? Auto insurers in Massachusetts offer a slew of discounts to help you save.
- Safe Driver Discount: Typically awarded to those with a clean driving record for a specific period.
- Multi-Policy Discount: Bundle your auto insurance with home or renters insurance for potential savings.
- Good Student Discount: If you’re a student with good grades, some insurers offer lower rates.
Each company has its unique offerings, so it’s crucial to ask and explore what’s available. Always leverage possible discounts to maximize your savings.
How to Save on Auto Insurance
Ever felt like your auto insurance premiums cost more than the car itself? You’re not alone. In Massachusetts, insurance can burn a hole in your wallet BUT you can take control.
There’s no magic bullet to slash your premiums overnight, BUT there are smart strategies you can use. Let’s dive into some actionable steps you can take to save big.
Strategies to Reduce Premiums
Step #1: Shop Around. Insurance rates can vary dramatically from one provider to another. It’s easy to assume all companies will offer similar rates, BUT that’s usually not the case. Compare quotes from at least three different insurers.
Step #2: Raise Your Deductible. By increasing your deductible, you can significantly lower your monthly premiums. Just make sure you can afford to pay the higher deductible in case of an accident.
Impact of Bundling Policies
Bundling your insurance policies is like hitting two birds with one stone. When you combine your auto insurance with other policies—like home or renters insurance—you can often snag a discount of up to 25%. Here is the deal: it’s not just about convenience; it’s about saving serious cash.
Common Discounts Available
Insurance companies offer a variety of discounts that are often overlooked. Here are some you should definitely consider:
- Good Driver Discount: If you have a clean driving record, you could save up to 20%.
- Safety Features Discount: Cars with anti-lock brakes and airbags can make you eligible for additional savings.
- Low Mileage Discount: Drive less, pay less. If you’re not racking up the miles, let your insurer know.
Pro Tip: Always ask your insurer about additional discounts. You might be eligible for savings you didn’t even know existed!
Importance of Regularly Reviewing Your Policy
Your life changes—and so should your insurance policy. Regularly reviewing your policy ensures that you’re not overpaying for coverage you no longer need. Check for duplicate coverages or unnecessary add-ons.
Step #3: Update Your Policy Annually. Take a fresh look at your insurance needs every year. Have you moved to a safer neighborhood? Bought a new car with better safety features? These changes can affect your premium.
Legal and Regulatory Aspects
Did you know that failing to have auto insurance in Massachusetts could cost you more than just a fine? Understanding the legal and regulatory landscape is crucial for any driver in the Bay State. Let’s dive into what you need to know.
Auto insurance regulations in Massachusetts are designed to protect both drivers and pedestrians. They ensure that everyone on the road can cover potential damages and injuries. The Massachusetts Division of Insurance plays a significant role in supervising these policies.
Regulatory Framework Governing Auto Insurance
Massachusetts operates under a “no-fault” insurance system. This means your insurance company will pay for your damages regardless of who caused the accident. Mandatory coverage includes personal injury protection (PIP), bodily injury liability, and property damage liability. Each has minimum coverage limits that you must meet.
The Role of the Massachusetts Division of Insurance
The Massachusetts Division of Insurance is the watchdog that ensures insurance companies adhere to state laws. They oversee the licensing of insurers, approve rates, and handle consumer complaints. This division ensures that policies are fair and affordable for consumers.
Penalties for Non-Compliance with State Insurance Requirements
Failing to comply with Massachusetts insurance requirements is no joke. If you’re caught driving without insurance, you could face fines, license suspension, and even jail time. The penalty for a first offense can be a fine up to $500 and a one-year license suspension.
Pro Tip: Always carry proof of insurance in your vehicle. It can save you from hefty fines and legal headaches.
Consumer Rights and Protections Under Massachusetts Law
Consumers in Massachusetts have rights when it comes to auto insurance. The law mandates that insurers must provide clear information about coverage options and costs. If you’re unsatisfied with your policy, you can file a complaint with the Division of Insurance for mediation. This ensures that you’re not left in the dark about your insurance coverage.
Future Trends in Auto Insurance
Ever wondered how technology will reshape auto insurance? It’s not just a thought experiment. It’s happening right now. And yes, it could dramatically impact your rates in Massachusetts.
Auto insurance is on the cusp of a high-tech revolution. Between telematics, usage-based insurance, and evolving environmental policies, there’s a lot to unpack. Let’s dive in and see what’s coming down the road.
The Impact of Technological Advancements on Insurance Rates
Technology is rapidly changing the insurance landscape. Self-driving cars and advanced safety features are becoming more common. This means fewer accidents and potentially lower insurance costs. BUT, here’s the deal: The cost of repairing these tech-heavy vehicles can be sky-high. So, while some aspects of technology may drive premiums down, others could push them up.
Pro Tip: Keep an eye on insurance policies that offer discounts for tech features in your vehicle.
The Influence of Telematics and Usage-Based Insurance
Telematics is transforming the way insurers evaluate risk. Rather than relying on traditional factors, telematics uses real-time data from your car. This could mean big savings if you’re a safe driver. But if you tend to speed, it might work against you.
In Massachusetts, usage-based insurance is gaining traction. It’s all about paying for the miles you drive. Imagine slicing your insurance bill by up to 30% just by driving less! That’s what you can expect with these new models.
Environmental Policies and Their Impact on Insurance
Environmental policies are increasingly influencing auto insurance. Massachusetts is pushing for greener practices, which might alter the auto insurance landscape. As electric vehicles become more popular, insurers may offer incentives for eco-friendly driving.
Expect to see more insurance options aimed at promoting sustainable vehicle choices. Who wouldn’t want to save the planet and some cash at the same time?
Demographic Changes and the Future of Auto Insurance
Demographics are shifting, and this could reshape the auto insurance industry. An aging population might drive less, reducing accident rates and potentially lowering premiums. However, younger generations have a different approach to car ownership. They’re more likely to use ride-sharing services, which could disrupt traditional insurance models.
This changing landscape means insurers need to adapt fast. The companies that innovate will be the ones you turn to for your coverage.
Closure
In the ever-evolving landscape of auto insurance in Massachusetts, staying informed is your best defense against soaring premiums. By understanding the nuances of coverage requirements, cost factors, and available discounts, you can not only save money but also ensure you have the protection you need on the road. Remember, a well-informed driver is a smart driver. Here’s to smoother rides and peace of mind on Massachusetts roads!
FAQ
What are the basic auto insurance requirements in Massachusetts?
In Massachusetts, drivers are required to have a minimum of liability insurance, personal injury protection (PIP), and uninsured motorist coverage. These components ensure that you’re covered for both your own expenses and those of others in the event of an accident.
How do factors like location affect auto insurance rates in Massachusetts?
Your location can significantly impact your insurance rates. Urban areas with higher traffic densities and accident rates often see higher premiums compared to rural regions.
Why is auto insurance in Massachusetts generally more expensive than in some other states?
Massachusetts ranks above average in terms of insurance costs due to factors like population density, accident frequency, and strict insurance regulations, all of which contribute to higher premiums.
Can my driving history influence my auto insurance rates in Massachusetts?
Yes, a clean driving record can help reduce your premiums, whereas a history of accidents or violations can lead to higher rates.
What discounts are commonly available for auto insurance in Massachusetts?
Common discounts include those for good driving, bundling policies, safety features, and even for being a loyal customer. It’s important to ask your insurer about all available discounts.
What is the role of the Massachusetts Division of Insurance?
The Massachusetts Division of Insurance regulates the insurance market to ensure fairness and compliance with state laws, protecting consumers’ rights.
How can technological advancements affect future auto insurance rates in Massachusetts?
Technological advancements, such as telematics and usage-based insurance, can lead to more personalized premiums and potentially lower costs for safe drivers.